

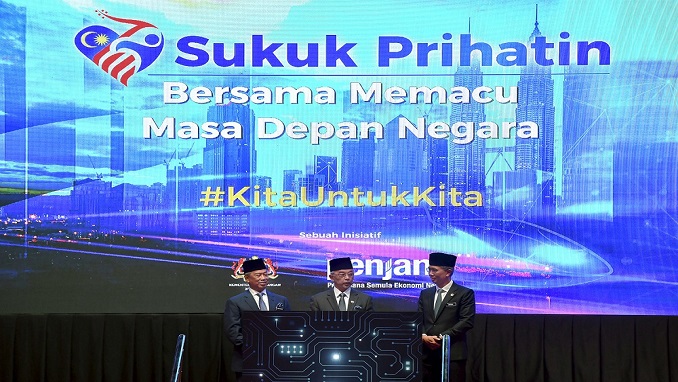

Malaysia’s maiden digital sukuk, the RM500 million Sukuk Prihatin, may not be enough to whet the rakyat’s “appetite” to help rebuild the domestic economy, economists said. They believed that the RM500 million issuance would be overly subscribed soon, and that another issuance could be on the cards.
Prime Minister Tan Sri Muhyiddin Yassin yesterday launched the Sukuk Prihatin, which aims to raise funds from the public and Corporate Malaysia wanting to contribute towards the national Covid-19 Fund. The two-year sukuk comes with a two per cent interest rate per annum and can only be subscribed through online banking channels JomPAY and DuitNow.
Putra Business School associate professor Dr Ahmed Razman Abdul Latif said there was a possibility for “Sukuk Prihatin Part Two”. He, however, said it depends on whether the additional fund was needed to achieve the same objectives or would there be additional needs to do so.
On Sukuk Prihatin’s low return of two per cent per annum, Ahmed Razman said this was due to its nature of being the most stable and secured sukuk.
“Since the sukuk is guaranteed by the government, there will be no losses on the investment. Hence, low risk, low return,” he told the New Straits Times.
Ahmed Razman added that the Sukuk Prihatin was more towards getting the people to contribute in helping the nation rather than pure investment product since the interest rate promised was rather low. He said the fund collected via the sukuk for the Covid-19 Fund would help the affected students in getting quality education as well as reducing the government’s financial burden.
The sukuk proceeds will also be used to provide further assistance to micro, small and medium enterprises, as the healthcare sector’s research on infectious diseases.
World Bank Group representative to Malaysia and country manager Dr Firas Raad said investors with fixed deposits would find the profit rate of 2.00 per cent to be favourable when compared with existing two-year bank deposit rates in the domestic commercial banking sector.
Firas said it was reasonably attractive compared to fixed deposit rates at major banks (CIMB Group Holdings Bhd and Malayan Banking Bhd’s rates for 24-month fixed deposits are 1.85 per cent).
“These investors would likely prefer to switch to Sukuk Prihatin given the slightly higher profit rate,” Firas added.
He said previous government bond issuances such as the Merdeka Savings Bond series targeted for citizens aged 56 and above had seen higher take-up rates than comparable fixed deposit rates at the time. The higher yield of Sukuk Prihatin should be similarly appealing to investors with cash holdings they do not need to use in the next 24 months, he added.
Firas said the corporate sector may not be as quick to invest as the larger corporates can negotiate with the banks for better rates on their fixed deposits and have access to the bond market.
“The Sukuk Prihatin is non-tradable and non-transferable, and in that sense, like a two-year fixed deposit that cannot be uplifted before maturity. Smaller corporates that normally only invest in fixed deposits, may be attracted to the slightly higher profit rate and tax-exempt status. However, given the current challenging economic situation, only those with excess cash reserves would be likely to invest, while others may skip it in favour of shorter-term fixed deposits to maintain liquidity,” he said.
Bank Islam chief economist Dr Mohd Afzanizam Abdul Rashid said the rate of return was decent considering that the country was in a low interest rate environment which was expected to prolong until next year.
“At the same time, the credit risks or risks of default is zero and therefore, it should give comfort to the sukuk holder. Will it attract buyers? From an asset allocation point of view, one needs to have high quality liquid assets and the sukuk is certainly meeting the criteria,” Afzanizam said.
In some sense, he added, the sukuk represented an opportunity for the rakyat to participate in helping the economic recovery especially those with extra cash.
Source New Straits Times