


Islamic banking, which is gaining popularity in emerging markets after helping some financial institutions avoid the worst of the economic meltdown, have been less affected than many conventional lenders in the recent global recession, which some nations are yet to surmount. This is mainly because unlike conventional banks, the Islamic banks have not been exposed to losses from investment in toxic assets nor have they been dependent on exotic derivative instruments since these practices are not in accordance with the principles set out in the Sharia Law.
For instance, Jaiz Bank said Islamic Banking (Non-Interest Banking) is a profitable growing global phenomenon practiced in nearly 70 countries across the world. Global banks such as HSBC, Citibank, Barclays Bank etc. also have windows for Islamic banking, which is an alternative financial service offering, which is open to all irrespective of race or religion. It is based on the ethical principles of fairness, transparency and integrity. Non-Interest Banking offers almost all the services of conventional banks. The difference is that non-interest Islamic banks do not give or receive interest, nor finance anything that is harmful to society such as alcohol, tobacco, gambling etc. They also seek to avoid gharar – (excessive speculation), uncertainty in contract and lack of transparency. Moreover, experiences of recent years have already indicated that the interest of people in Islamic banking goes beyond only Islamic investors. The UK is said to be the hub of Islamic Banking in the world, yet only 5 per cent of its population are Muslims. Consequently, governments and regulators in a variety of countries – Nigeria inclusive, have already recognized the importance of Islamic banking as a feasible alternative to conventional banking.
Market analysts believe that inability of the present administration in Nigeria to give the economy clear direction made investors – especially foreigners to remain on sideline until they had a clear picture of the policy direction of the government. These microeconomic pressures and unrelenting regulatory adjustments had to a large extent constrained the margins of financial institutions in the country, which Jaiz Bank, the only non-interest bank quoted on the stock market was not exempted from.
The bank, which showed positive performance across all financial indices in 2017, has recorded decline in the first and second quarters of 2018. The bank’s share price, which closed at 70 kobo per share last September, has declined considerably. At the close of business last Friday, the share price had dropped to 58 kobo per share, a decrease of 12 kobo or 17.14 per cent year to date.
The profit margin of the bank began to recede in the first quarter ended March 31, 2018 as the key highlights of the results showed that the lender reported gross income of N1.57 billion for the period ended March 2018 compared to N1.54 billion reported for the period ended March 2017. This represents a two per cent increase for the comparative period in 2017.
Profit before tax was N146.57 million for the period ended March 2018, a 28 per cent decrease from the N203.68 million reported for the period ended March 2017. Jaiz Bank also reported earnings per share of 0.5 kobo for the period ended March 2018 compared to 0.69 kobo reported for the period ended March 2017. This represents a 28 per cent decrease for the comparative period in 2017.
Jaiz Bank Plc, a non-interest bank quoted on the floor of the Nigerian Stock Exchange (NSE) reported a decline of 54.98 per cent in profit after tax for the six months ended June 30, 2018. Profit before tax stood at N231.215 in 2018 from N540.207 million a year earlier. However, income rose by 4.60 per cent from N2,953 billion in 2017 to N3,089 billion in 2018.
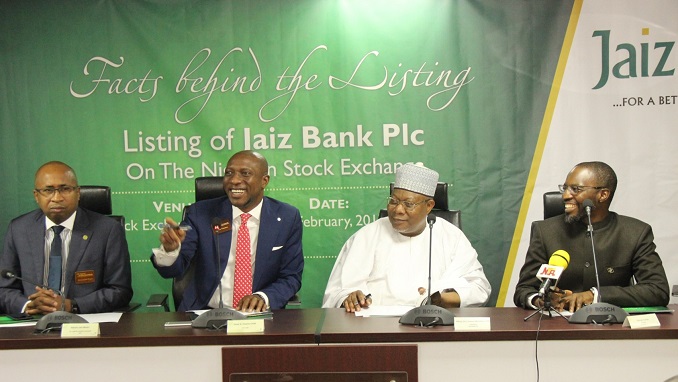
Jaiz Bank Plc intends to growing its profit after tax to N3.827 billion in the next five years. The Managing Director/CEO of the bank, Hassan Usman, who stated this while addressing investment community at the bank’s facts behind the figures on the floor of the NSE, also projected to grow the company’s total assets from N123.612 billion in 2018 to N262.804 billion in 2022.
Multiple challenges arising from a weaker macroeconomic environment and the various regulatory responses had put significant pressure on the margins of banks. However, it is hoped that transformational strategies of the bank may bring positive changes.
Source New Telegraph